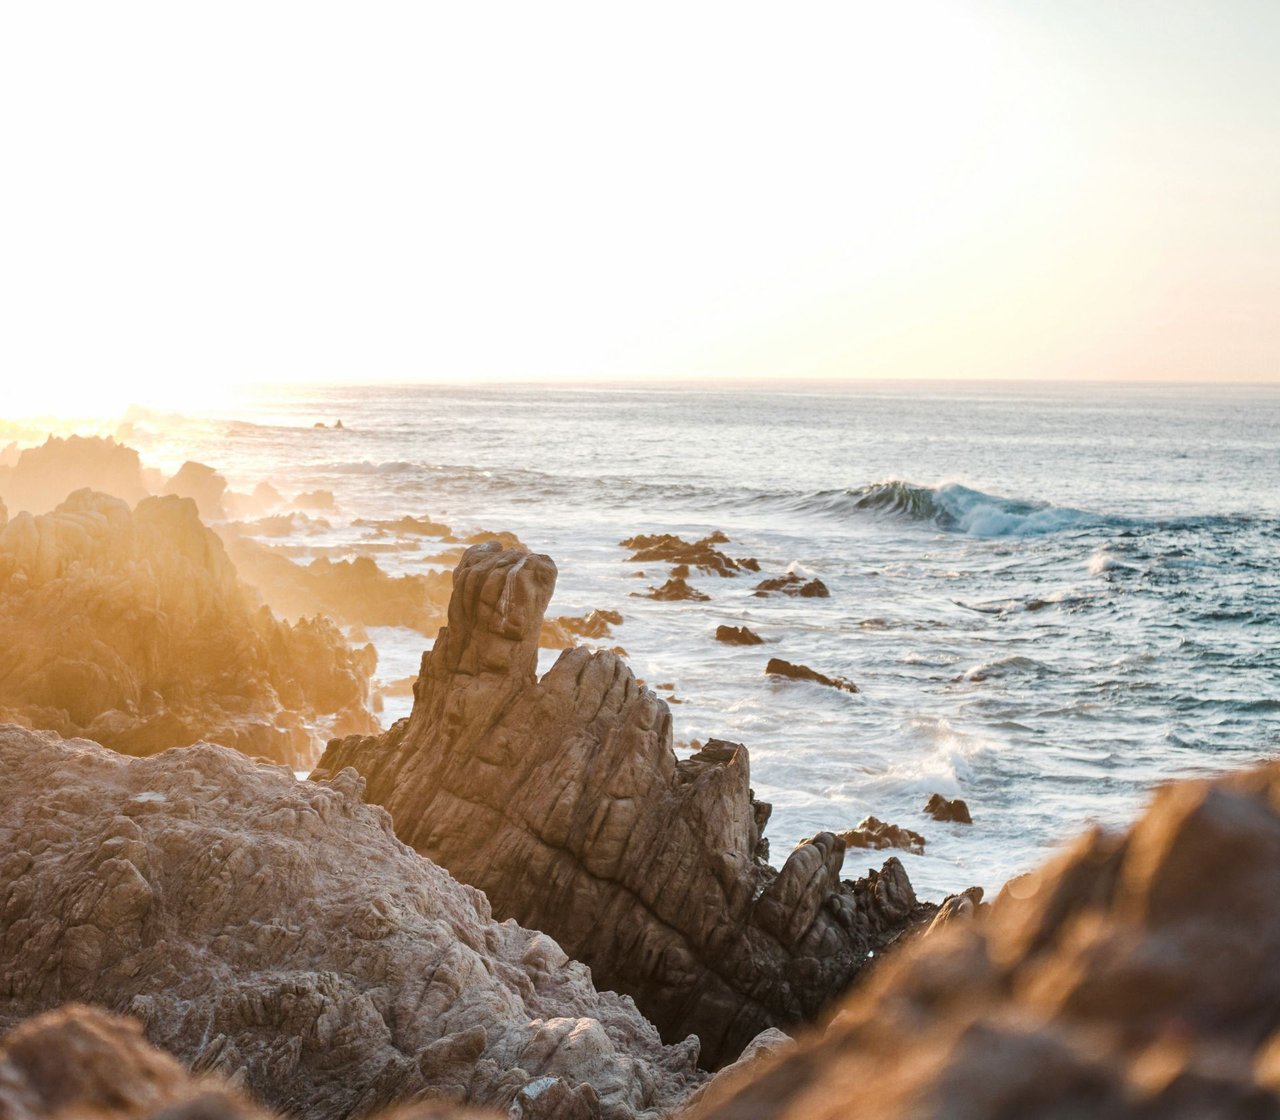
At 7:15 in the morning on January 31, 2025, Laguna Beach's Emergency Communications Center took a call about bluff movement near Point Place, the stretch of coastline between 9th and 10th Street Beach that most people know by its nickname: Thousand Steps. By the time crews arrived, roughly 500 cubic yards of bluff material had already come down onto the sand. Private access stairways and walkways were damaged. Three homes above the slide were evacuated as a precaution. A search and rescue dog checked the debris field to make sure no one was caught in it. No one was. According to the city's own account, no structures were directly impacted either.
Eighteen months later and a few miles down the coast, it happened again. On or around June 15, 2026, a section of bluff above Brooks Street gave way after a run of South Pacific swell collided with exceptionally high king tides. Officials cordoned off the viewing area while engineers checked what was left of the cliff. A longtime regular at the break, former pro surfer Jeff Booth, put it simply after watching the swell build for days: "We had been watching this and knew it was a matter of time."
Two collapses, a few miles of coastline apart, both following the same pattern. Storm energy soaks into the bluff base, destabilizes what's underneath, and the visible failure shows up days later once the water has already receded. If you're shopping or selling a hillside or bluff-top home here, that pattern is worth understanding. But it isn't the part of this story that should be steering your escrow.
What the Record Actually Shows
Here's the detail that tends to get lost once a bluff collapse makes the news: in both 2025 and 2026, city officials said the same thing.
| Event | Material lost | Access infrastructure affected | Reported damage to homes |
|---|---|---|---|
| Thousand Steps, Jan. 31, 2025 | ~500 cubic yards | Private and public stairways damaged | None reported |
| Brooks Street, June 2026 | Section of bluff face | Public viewing area cordoned off | None reported |
Twice in eighteen months, the failure took out public or shared access infrastructure and left the homes above standing. That isn't a guarantee about the next storm. It is, however, a useful correction to the instinct that a bluff-top listing in Laguna Beach is one bad swell away from a structural crisis. The geology here is managed, permitted, and setback-regulated in ways that have already absorbed two real events without a home coming down.
Which raises the actual question: if the bluff itself isn't what typically derails these deals, what is?
The Setback Rule That Already Did Its Job
Laguna Beach's Local Coastal Program was certified by the California Coastal Commission on January 13, 1993, and it's the reason bluff-top construction here looks the way it does. The city and the Commission have consistently applied a 25-foot setback from the identified bluff edge for new residential structures, with a tighter 10-foot line for accessory structures that don't require a foundation, like decks and walkways. That consistency matters more than it sounds. Every appeal the Commission has heard on this point, including recent ones over blufftop remodels, has reinforced the same 25-foot line rather than carving out exceptions.
Four small enclaves sit outside the city's certified jurisdiction entirely: Three Arch Bay, Blue Lagoon, Hobo Canyon, and Irvine Cove. In those pockets, the California Coastal Commission still issues coastal development permits directly rather than delegating that authority to the city, which means a remodel or rebuild there runs through a different, often slower review than the rest of Laguna's bluff-top inventory. If you're comparing two similar-looking bluff lots in different neighborhoods, that jurisdictional split is worth knowing before you assume the permitting timeline will match.
None of this is new information invented by the recent slides. It's the regulatory floor that was already in place when both bluffs failed, and it's a large part of why neither failure took a house with it.
The Mechanism That Actually Changed
Here's the shift that the two bluff events expose, once you look past the geology: the thing that increasingly decides whether a Laguna Beach hillside deal closes on schedule isn't the bluff report. It's the insurance quote.
California's standard homeowners insurance market has pulled back hard from wildfire and hillside exposure statewide, and that pullback has moved from rural and canyon-adjacent communities into coastal cities that don't fit the old mental picture of fire risk. Laguna Beach itself sits partly within Very High Fire Hazard Severity Zones, a designation that triggers mandatory disclosure and, increasingly, non-renewal notices from carriers who once wrote these hillside policies without a second look. The hillside neighborhoods most exposed to that shift include areas like Top of the World and Arch Beach Heights, where ridgelines climb to grades above 30 percent.
When a standard carrier declines the risk, the fallback is the California FAIR Plan paired with a separate Difference in Conditions policy to cover what FAIR Plan leaves out, since it insures only fire, smoke, and explosion. Combined, that pairing can run $8,000 to $18,000 a year for an Orange County hillside home, a cost that shows up nowhere on the seller's disclosure form and everywhere in a buyer's loan qualification. State regulators have acknowledged the strain the FAIR Plan itself is under. In 2026, Insurance Commissioner Ricardo Lara and the legislature introduced reforms aimed at improving how the FAIR Plan handles claims and coverage after years of complaints from wildfire survivors trying to get paid.
The practical result is a market that increasingly sorts itself by who can absorb that cost without financing contingencies. Buyers who can pay cash aren't waiting on a lender's insurance requirement, which is part of why fire-zone hillside listings in Orange County skew more heavily toward cash offers than the broader market. And pricing has started to reflect it. Analysis of Laguna Beach and Anaheim Hills sales from 2023 through 2025 shows homes in the highest fire-risk tier selling at a 5 to 12 percent discount compared to similar homes in lower-risk zones nearby, a gap that has nothing to do with the view or the finishes and everything to do with what it costs to insure the roof over them.
Three Things Worth Pulling Before You're in Contract
If you're buying or selling a bluff-top or hillside property in Laguna Beach, the paperwork that actually protects you looks less like the standard disclosure packet and more like this:
- A buyer's geotechnical update. A standard home inspection does not evaluate bluff stability. A letter of opinion from a qualified geotechnical engineer, factoring in the property's slope grade and any prior remediation, typically runs $3,000 to $8,000. Bluff lots and homes with a history of repair land at the higher end.
- An insurance quote pulled during your contingency period, not after. Waiting until after close to learn a property can't get standard coverage is the most common way these deals get renegotiated at the worst possible moment. Sellers who pull their own quotes before listing and share the numbers upfront tend to keep more of their asking price intact.
- Confirmation of which permitting track applies. Ask whether the parcel sits inside the city's certified LCP jurisdiction or in one of the four enclaves the Coastal Commission still reviews directly. It changes your renovation timeline even if it changes nothing about the home itself today.
One more thing worth knowing if you're picturing a seawall as your backstop: the Coastal Commission has consistently favored managed retreat over new armoring as bluff erosion accelerates, and getting a shoreline protective device approved for a private residence is a deliberately difficult process that often ends in denial. A bluff event happening near your property does not automatically clear the path to build a wall.
What This Means If You're Deciding Right Now
Laguna Beach's bluff-top and hillside inventory hasn't gotten more dangerous in the way the news coverage of two collapses might suggest. The geology is doing roughly what the 1993 setback rules were designed to have it do. What's shifted is the financial layer sitting on top of the geology: an insurance market that treats these hillsides differently than it did three years ago, and a pricing gap that's already showing up in the comps if you know where to look.
That's the part of the transaction where a tax and finance-aware read of the deal actually earns its keep, separate from whether the bluff itself looks stable on a site visit.
A Short FAQ
Does a bluff collapse near my property affect what I have to disclose as a seller? California's Natural Hazard Disclosure requirements already cover flood, fire, and earthquake zone designations regardless of whether a nearby bluff has recently failed. A collapse on a neighboring or public parcel doesn't create a new disclosure category on its own, though any known material facts affecting your specific property still need to be shared.
If my home is in a Very High Fire Hazard Severity Zone, does that automatically mean I can't get standard insurance? Not automatically, but it does trigger more scrutiny from carriers, and non-renewal notices have become more common in these zones over the past two years. Getting a quote early in the process, rather than assuming coverage will be available, is the safer approach.
Is the 25-foot bluff setback the same everywhere in Laguna Beach? The city and Coastal Commission have applied it consistently across the certified jurisdiction, but the four deferred-certification enclaves, Three Arch Bay, Blue Lagoon, Hobo Canyon, and Irvine Cove, fall under the Commission's direct review rather than the city's, which can change both the process and the timeline.
If you're weighing a bluff-top or hillside purchase or sale in Laguna Beach and want the insurance and geotechnical picture laid out before you write an offer, not after, Jeff Engstrom - Orange County can walk through what a specific property is actually carrying. Schedule a Free Tax-Smart Home Consultation and get the numbers before they become a renegotiation.